The cause and the policy both matter
The California Department of Insurance explains that damage from rain entering through a roof opening may generally be covered when the opening was caused by a peril covered by the policy. Its homeowners guide also lists exclusions including wear and tear, maintenance and certain leaks. Ask the insurer how the policy applies to the assessed facts.
This distinction matters: water appearing after rain does not establish the cause of the opening or the scope of coverage. Fountain RoofLink does not interpret your policy, adjust claims or promise that an insurer will approve work.
Questions to put to the insurer
- What information do you need about the date and suspected cause?
- How does my policy distinguish the roof defect from resulting indoor damage?
- Which exclusions, deductible and settlement terms should I understand?
- What photographs, inspection records or receipts should I retain?
- What steps should I take before authorizing temporary protection or permanent work?
Keep a factual record
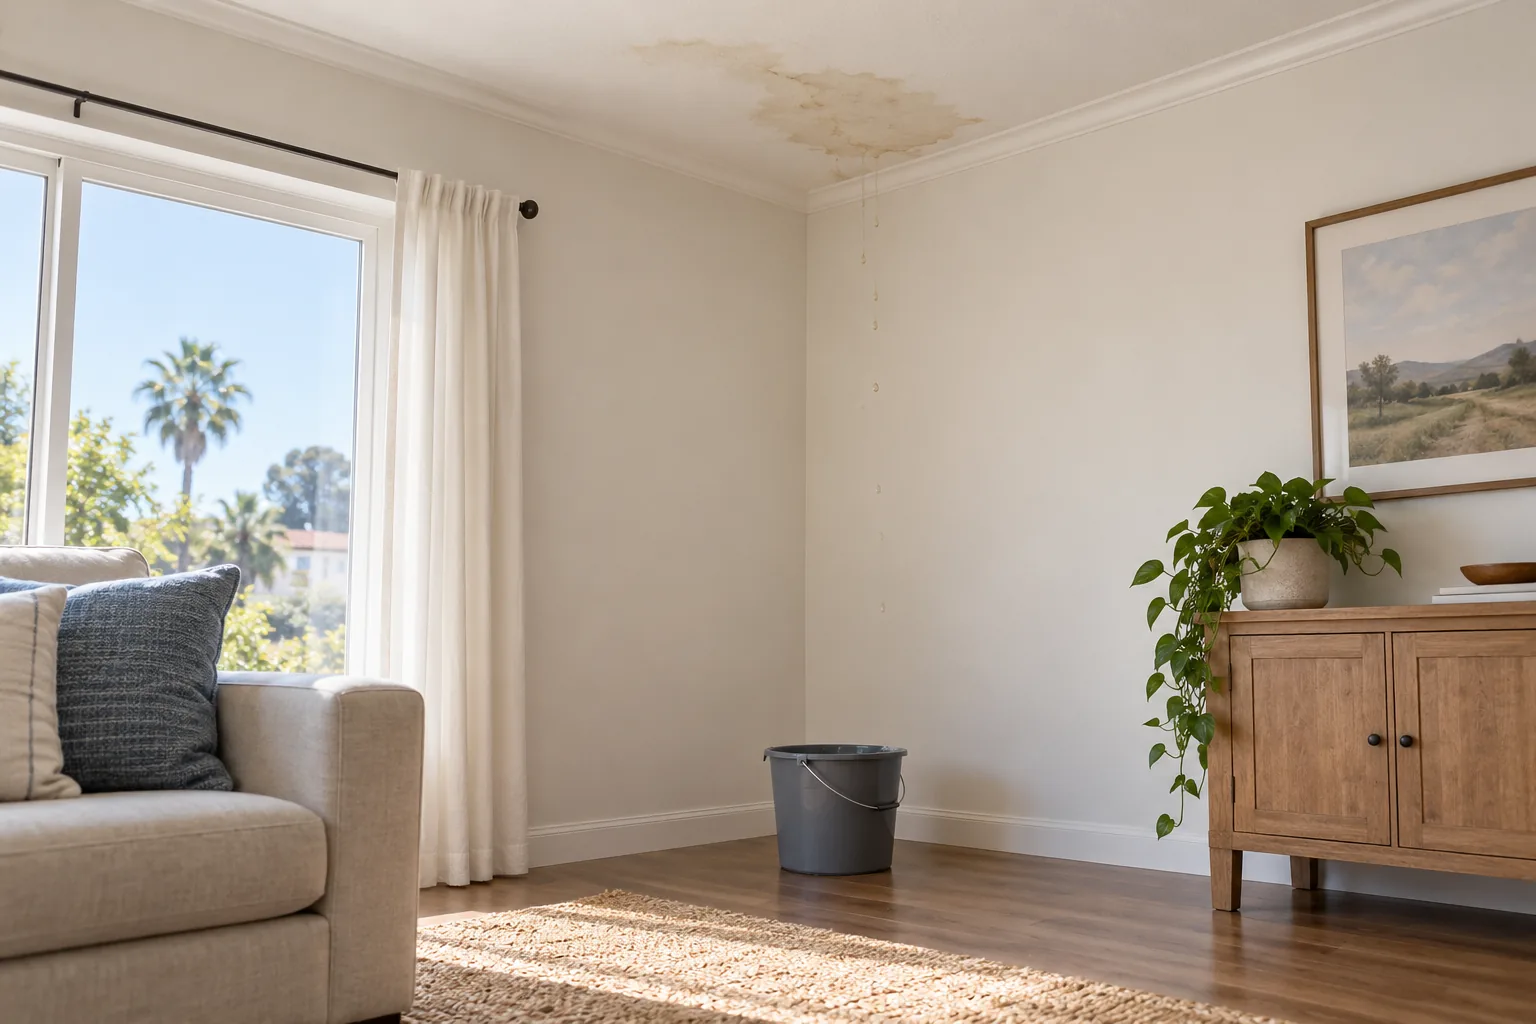
Record when you first noticed the issue and keep dated photographs taken from a safe place. Retain the provider's assessment and written scope. Avoid attributing all observed damage to a storm simply because that was when you noticed the stain.
What should I ask the roofing provider?
Ask them to describe the observed roof condition and proposed work accurately. Clarify whether the scope concerns temporary protection, a permanent roof repair or separate interior finishing. The provider's assessment and the insurer's coverage decision serve different purposes.
Get the right kind of answer
Questions about coverage belong with the insurer or a properly qualified insurance professional. Questions about the physical roofing condition belong with an appropriate contractor. A referral website cannot replace either assessment.
For help preparing observations, read what to record before calling. For a current weather-related concern, see our storm damage enquiry page. Review the California Department of Insurance resources below for the source guidance.
Sources & further reading
California Department of Insurance: residential property claims ↗California Department of Insurance: homeowners insurance guide ↗General homeowner information, prepared 21 October 2026. These resources do not imply affiliation or endorsement. The provider assesses the property; the insurer decides policy coverage.